Social Security & Medicare
Two decisions, one plan
We help you understand when to claim Social Security, how to set up Medicare, and how the two connect.
Social Security
- Your claiming age, from 62 to 70
- Spousal and survivor benefits
- The earnings test
- Taxes on your benefits
Medicare
- The four Parts of Medicare
- Medigap or Medicare Advantage
- Prescription drug coverage
- Income-related premiums (IRMAA)
Why it matters
When you claim matters
Deciding when to claim Social Security is a lasting decision, so it helps to understand the options first.
-
Your claiming age
You can claim as early as 62 or wait until 70. Full retirement age is 67 for anyone born in 1960 or later. Claiming early lowers your monthly benefit; each year you wait past full retirement age raises it by 8 percent, up to age 70. Your health, family longevity and other retirement income all weigh on the choice.
-
Spousal and survivor benefits
Married couples have claiming options of their own. When the higher earner claims affects the survivor benefit the surviving spouse may receive later.
-
The earnings test
If you claim before full retirement age and keep working, part of your benefit may be withheld when your earnings pass a yearly limit. Withheld amounts are generally accounted for later.
-
Taxes on your benefits
Depending on your provisional income, up to 85 percent of your benefits can be subject to federal income tax. The accounts you draw from in retirement can affect this.
Medicare
The four Parts of Medicare
With several Parts and many plan choices, it helps to see the building blocks first.
-
Part A, hospital insurance
Inpatient hospital stays, skilled nursing facility care, hospice and some home health care. Most people who worked about 10 years pay no premium.
-
Part B, medical insurance
Doctor visits, outpatient care, medical equipment and preventive services, with a monthly premium set each year.
-
Part C, Medicare Advantage
Plans from private insurers that bundle Parts A and B, and usually Part D, into one plan.
-
Part D, prescription drugs
Prescription coverage from private insurers, with a yearly limit on what you pay out of pocket for covered drugs.
Filling the gaps
Medigap or Medicare Advantage
The two common ways people cover what Original Medicare leaves open.
| Feature | Original Medicare with Medigap | Medicare Advantage (Part C) |
|---|---|---|
| Choice of doctors | Any doctor or hospital in the US that accepts Medicare | Usually a local HMO or PPO network; referrals may be needed |
| Costs | A higher monthly premium, with lower costs when you get care | Often a lower monthly premium, with copays up to a yearly out-of-pocket maximum |
| Prescription coverage | Bought separately as a Part D plan | Usually included in the plan |
| Travel | Coverage across the US; some Medigap plans include emergency care abroad | Mainly local, with emergency and urgent care outside the plan area |
IRMAA
Income and your Medicare premiums
If your modified adjusted gross income from two years earlier is above thresholds set each year, Medicare adds an income-related monthly adjustment amount, known as IRMAA, to your Part B and Part D premiums.
-
Managing your tax bracket ahead of time
Because IRMAA looks back two years, decisions such as Roth conversions or large withdrawals in the years before Medicare can affect your premiums later. They are worth weighing with your tax professional.
-
Appealing after a life-changing event
If your income has dropped because of retiring, divorce or the loss of income-producing property, you can ask Social Security to use your more recent income by filing form SSA-44.
An integrated approach
How the decisions connect
Social Security claiming affects your taxes and your Medicare premiums, so these decisions should not be made in silos.
-
Your claiming age
When you start Social Security changes your income, and with it how much of your benefit is taxed.
-
Your taxable income
Your income from two years earlier sets whether IRMAA is added to your Medicare premiums.
-
Your withdrawals
Which accounts you draw from shapes your taxable income, and so both of the above.
Our team
Meet who’s here
Licensed financial professionals, guided by WFG and WSB expertise, here to walk you through each step.
Meet the Full Team-
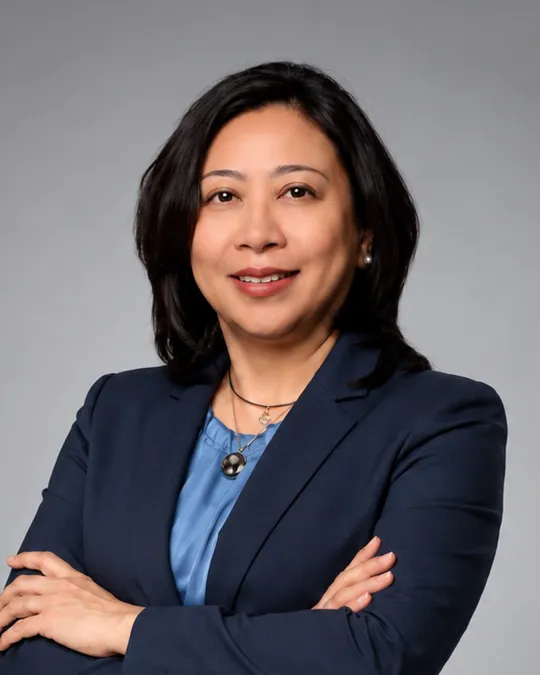
Dr. June Magallanes
CEO
-
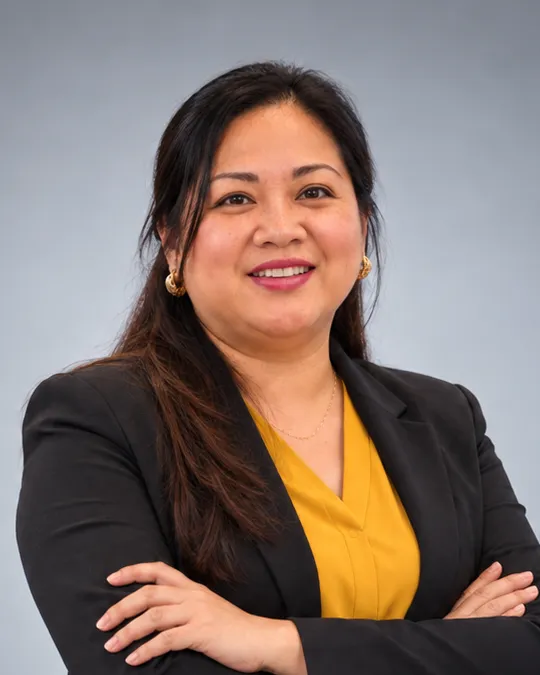
Ms. Lorraine Go
Senior Marketing Director
-
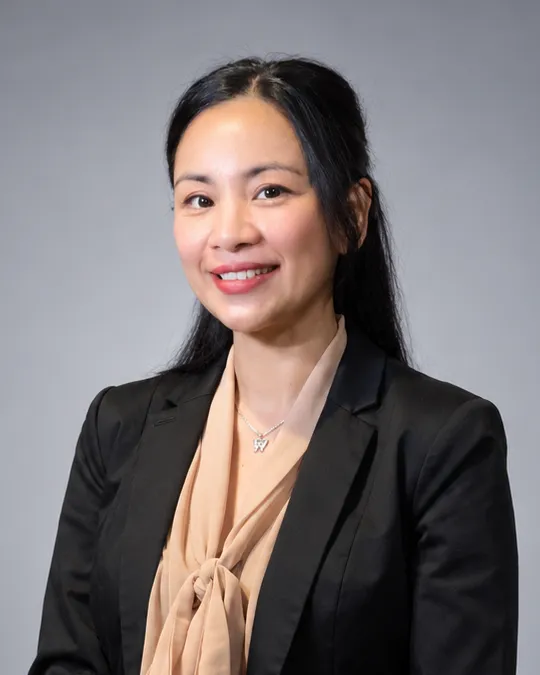
Aileen Marie Mapalo
Senior Marketing Director
-
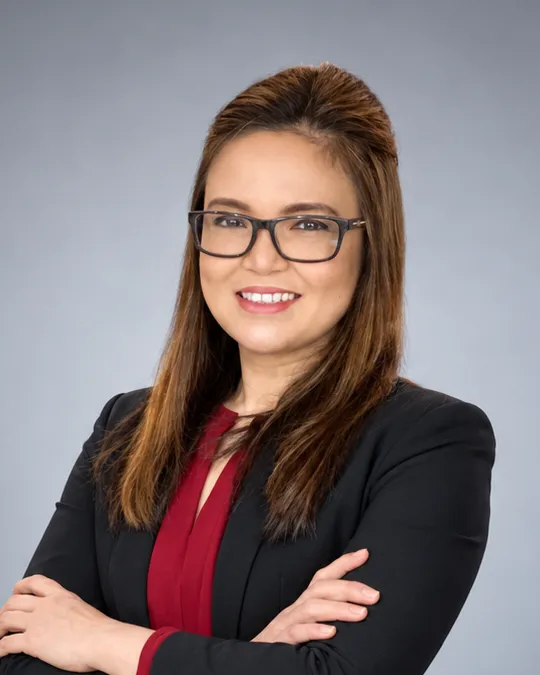
Mary Carmel Elizon
Senior Marketing Director
-
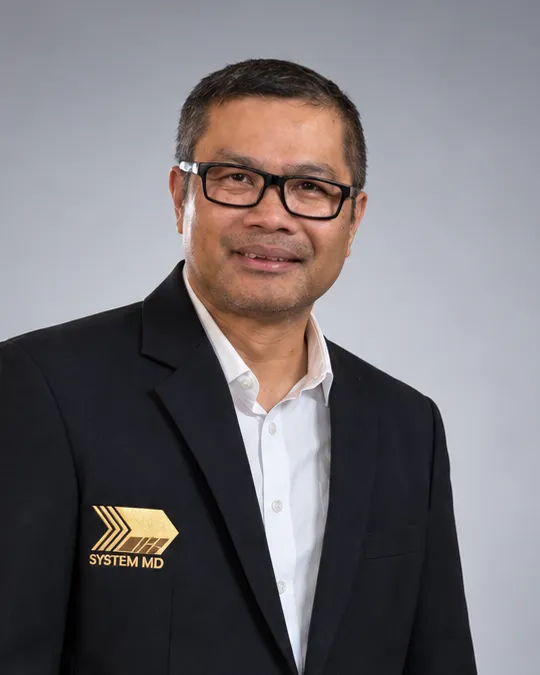
Michael Damot
Senior Marketing Director
-
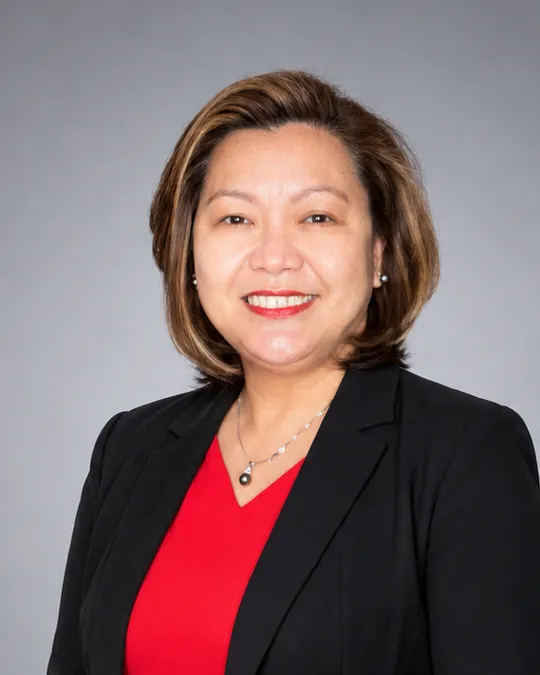
Sheila Albelda
Senior Marketing Director
FAQs
Answers to questions we hear often. They explain how things work; your own situation is worth a conversation.
-
What is full retirement age?
The age at which you can receive your full Social Security benefit. It is 67 for anyone born in 1960 or later. You can claim as early as 62 for a reduced benefit, or wait until 70 for a larger one.
-
What is provisional income?
The measure Social Security uses to decide how much of your benefit is subject to federal income tax. Depending on it, up to 85 percent of your benefits can be taxable.
-
What does Original Medicare leave uncovered?
Original Medicare, Parts A and B, includes 20 percent coinsurance for most Part B services with no yearly limit on what you pay. Most people fill that gap with a Medigap policy or a Medicare Advantage plan.
-
Is Part A free?
Part A is premium-free for most people who have worked 10 or more years.
-
Does Social Security keep up with inflation?
Benefits are adjusted each year for the cost of living, and they continue for life.
-
Where can I see every Medicare plan in my area?
Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Assistance Program (SHIP) can give you information on all of your options.
Talk it through with our team
For one-on-one questions, a Complimentary Financial Check-Up is a good place to start.
Book an AppointmentLearn alongside others
Our financial literacy workshops are listed on our calendar, and organizations can request one of their own.
See the Workshops
Resources & tools
Free tools to see your numbers clearly
No sign-up, no cost. Enter a few numbers, answer a few questions, and get a clearer picture before you ever sit down with Dr. June.
-
Savings Calculator
See how steady deposits and compound interest work together to grow your savings over time.
-
Debt Roll-Up Calculator
Map out a debt snowball: clear one balance, then roll that payment into the next until every debt is paid.
-
Risk Profile Questionnaire
Nine quick questions to help you understand your own comfort with financial risk, and your ability to take it.