Life Insurance
Coverage shaped around your family
We explain your options side by side, so you can choose coverage that fits your goals, your budget and the years you need it.
Coverage we explain
- Term life insurance
- Whole life insurance
- Universal life insurance
- How cash value works
What we look at
- The income your family relies on
- Your mortgage and other debts
- Education and future goals
- How your estate passes on
Why it matters
A safety net for the people you love
None of us can predict the future. A well-chosen policy can help protect your family's standard of living when they need it most.
-
Replace lost income
Help your family keep covering day-to-day living expenses without your income.
-
Settle outstanding debts
Help keep loved ones from inheriting a mortgage, personal loans, car payments or credit balances.
-
Fund future plans
Set money aside for your children's education, major life events or the next generation.
-
Cover final expenses
Ease the cost of funeral expenses and medical bills during an emotional time.
-
Plan how wealth passes on
Life insurance can be part of how an estate passes to the next generation. How it is taxed depends on your situation.
Types of coverage
Two main kinds of life insurance
Most policies are either term, for a set period, or permanent, for life. Choose one to see how it works.
Life insurance options
Term life insurance
How it works
Straightforward coverage for a set period, typically 10, 15, 20 or 30 years. If the insured person passes away during the term, the beneficiaries receive the death benefit.
Often chosen by
People who want the most coverage for their budget, especially young families, homeowners with a mortgage, and people covering their earning years.
- How long it lasts
- A set period
- Cash value
- None, a death benefit only
At a glance
- A specific period Coverage for 10 to 30 years, matched to the years you need it most.
- Affordable and simple Premiums typically start lower than for permanent coverage.
- A pure death benefit It pays a death benefit, with no cash value.
Permanent life insurance
How it works
Lifelong coverage as long as premiums are paid. Along with the death benefit, it builds cash value that grows tax-deferred, which you may borrow against or withdraw for future needs.
Worth knowing
Loans and withdrawals reduce the cash value and the death benefit. Guarantees depend on the claims-paying ability of the issuing insurer.
- How long it lasts
- For life
- Cash value
- Grows tax-deferred
Types of permanent coverage
- Whole life insurance Premiums and the death benefit are set when the policy is issued, and cash value grows on a predictable schedule. Often chosen for certainty and lifetime protection.
- Universal life insurance Flexible coverage with adjustable premiums and death benefits. Cash value earns interest based on current rates or index performance, so it can adapt as your situation changes.
Term or permanent
The two side by side
How the two kinds of coverage compare, and who each one often suits.
| Feature | Term life insurance | Permanent life insurance |
|---|---|---|
| How long it lasts | A set period, typically 10, 15, 20 or 30 years | Your whole life, as long as premiums are paid |
| What it pays | A death benefit if you pass away during the term | A death benefit, plus cash value you may borrow against or withdraw |
| Cash value | None | Grows tax-deferred over time |
| Premiums | Typically lower to start | Typically higher, for lifelong coverage |
| Often chosen by | Young families, homeowners with a mortgage, people covering their earning years | People who want lifetime protection alongside their wider plans |
Our team
Meet who’s here
Licensed financial professionals, guided by WFG and WSB expertise, here to walk you through each step.
Meet the Full Team-
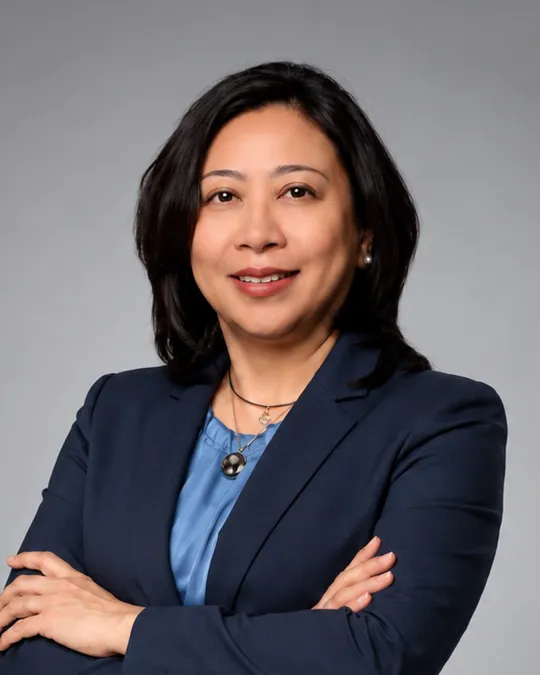
Dr. June Magallanes
CEO
-
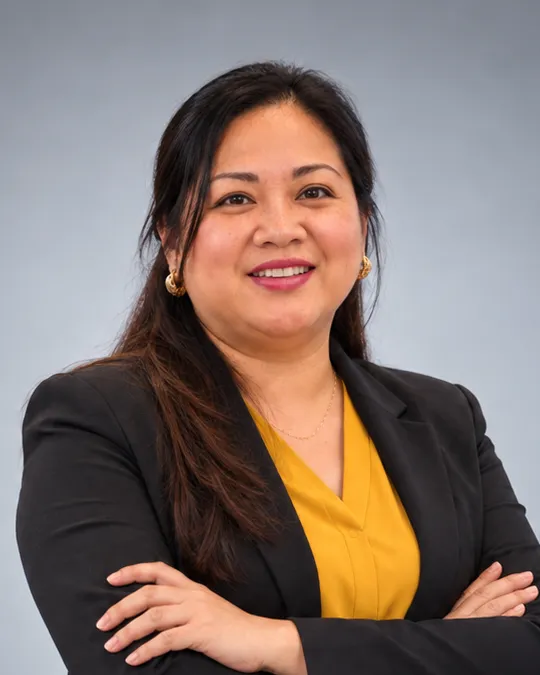
Ms. Lorraine Go
Senior Marketing Director
-
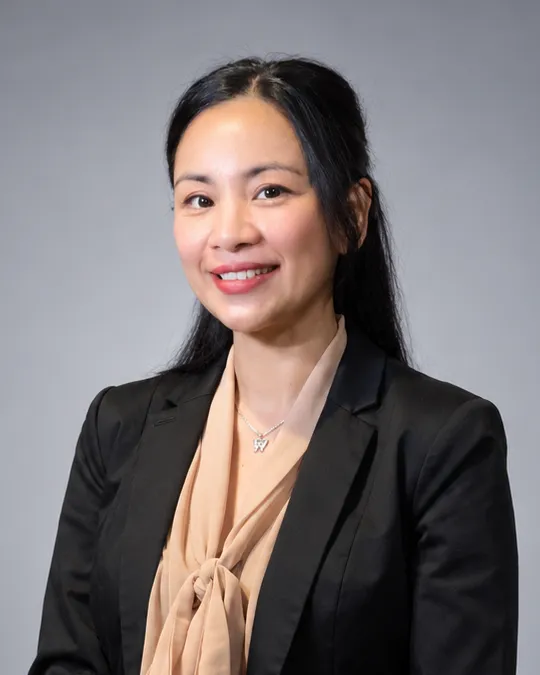
Aileen Marie Mapalo
Senior Marketing Director
-
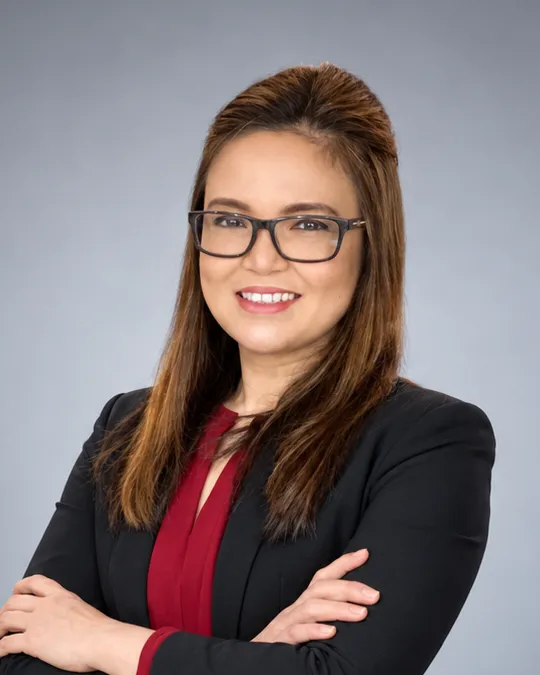
Mary Carmel Elizon
Senior Marketing Director
-
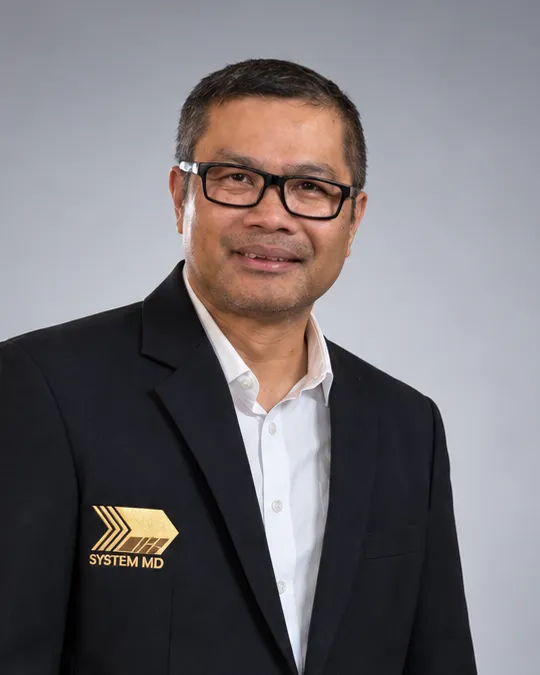
Michael Damot
Senior Marketing Director
-
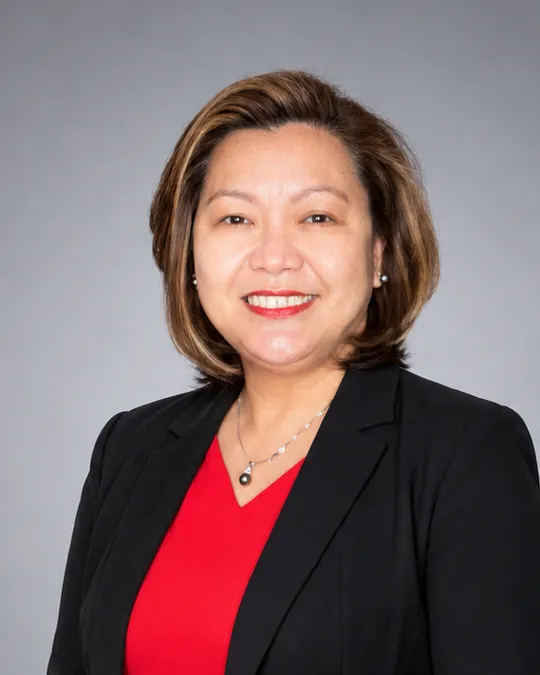
Sheila Albelda
Senior Marketing Director
FAQs
Answers to questions we hear often. They explain how things work; your own situation is worth a conversation.
-
What is term life insurance?
Term life insurance covers a set period, typically 10, 15, 20 or 30 years. If the insured person passes away during the term, the beneficiaries receive the death benefit.
-
Who often considers term coverage?
People who want the most coverage for their budget, especially young families, homeowners with a mortgage, and people covering their main earning years. Premiums typically start lower than for permanent coverage.
-
What is permanent life insurance?
Coverage designed to last your whole life, as long as premiums are paid. Along with the death benefit, it builds cash value that grows tax-deferred over time, which you may be able to borrow against or withdraw for future needs. Loans and withdrawals reduce the cash value and the death benefit, and can have tax consequences.
-
Can I use the cash value in my policy?
With permanent coverage, you may be able to borrow against or withdraw cash value for future needs. Loans and withdrawals reduce the cash value and the death benefit, and can have tax consequences.
-
How much coverage might I need?
It depends on who relies on your income and for how long, the debts that would need paying, the goals you want covered and what fits your budget. A Complimentary Financial Check-Up is a good place to work through it.
-
Are the guarantees in a policy certain?
Guarantees in a life insurance policy depend on the financial strength and claims-paying ability of the issuing insurance company.
Talk it through with our team
For one-on-one questions, a Complimentary Financial Check-Up is a good place to start.
Book an AppointmentLearn alongside others
Our financial literacy workshops are listed on our calendar, and organizations can request one of their own.
See the Workshops
Resources & tools
Free tools to see your numbers clearly
No sign-up, no cost. Enter a few numbers, answer a few questions, and get a clearer picture before you ever sit down with Dr. June.
-
Savings Calculator
See how steady deposits and compound interest work together to grow your savings over time.
-
Debt Roll-Up Calculator
Map out a debt snowball: clear one balance, then roll that payment into the next until every debt is paid.
-
Risk Profile Questionnaire
Nine quick questions to help you understand your own comfort with financial risk, and your ability to take it.